How much is flood insurance in Louisiana? There is no single price that fits every property. The cost of a policy depends on the property’s location and flood exposure. How the building was constructed, what you insure, the deductible, and the terms of the policy.
Contact GAMA with your flood insurance questions
In brief, a quote is shaped by the risk and characteristics of the specific building, the limits and deductibles selected, and the insurer or programme offering coverage. Two homes on the same street can have different quotes if their elevation, foundation, age, construction, or coverage choices differ. The best comparison is not simply the lowest premium. It is a side-by-side review of what each policy protects, what it excludes, and what you would pay after a covered loss.
Have questions about flood coverage? Contact GAMA for general guidance.
How much is flood insurance in Louisiana, and why does it vary?
There is no single answer to how much is flood insurance because a flood-risk assessment is tied to the individual property, not simply its city or parish. A home in Kenner, New Orleans, Baton Rouge, or a River Parishes community can present different characteristics, even when the addresses are relatively close. FEMA’s Risk Rating 2.0 methodology uses the building’s address and other property-specific information when assessing flood risk. FEMA’s rating guide explains that the approach considers the individual building rather than relying on a single broad label.
Address, water and elevation
Location remains important for several reasons. The assessment can consider the property’s distance from a flooding source, including the coast, rivers and other waterways. It can also consider the ground elevation where the building sits relative to the surrounding area and nearby sources of flooding. That means two properties in the same neighbourhood may not receive the same evaluation if one is closer to water or sits at a different elevation.
Louisiana’s varied geography makes this especially relevant. Coastal exposure, river systems, drainage conditions and local development patterns can all contribute to different flood circumstances. A property outside an area commonly regarded as high risk should not automatically be assumed to have no flood exposure. The location and building details still need to be reviewed in context.
Community and property information
The community where a building is located may also form part of the assessment. FEMA identifies community characteristics, including how a community relates to the Community Rating System, as a possible rating consideration. Insurers or programme administrators may also need accurate information about the property’s use, foundation, floor height and other construction details. Providing an incomplete or outdated address, elevation detail or building description can make a quote evaluation less reliable.
For general homeowners coverage context, review GAMA’s homeowners insurance information. Flood coverage is policy-specific, so treat any online estimate as a starting point and check the final terms, exclusions and assumptions before making a decision.
How does location and flood exposure affect a quote?
Insurers consider where a property is and the kinds of water exposure that may affect it. A map or zone designation can be one input, but it does not tell the whole story. Rainfall flooding, storm surge, overflowing waterways, and drainage-related water can create different exposures. Nearby canals, ditches, levees, wetlands, and changes in the surrounding landscape may also shape a property’s risk profile. The insurer’s assessment and policy definition determine which details affect the quote.
Conditions can vary within Kenner, greater New Orleans, Baton Rouge, and other parts of Louisiana. A property close to water is not automatically assigned the same price as another property nearby. The building’s elevation, foundation, drainage and construction, along with the coverage requested, may distinguish the quotes. Likewise, a property outside a mapped high-risk area may still face flood exposure. Maps and public records should be treated as information to discuss, not a promise of safety or an individual insurance determination.
When you request a quote, provide the full property address and correct building details. A quote based on an approximate location or assumptions about the structure may need to be revised after verification. If you are considering a purchase, ask about flood coverage early enough to understand the terms before your transaction timeline becomes tight.
Which building characteristics can change the price?
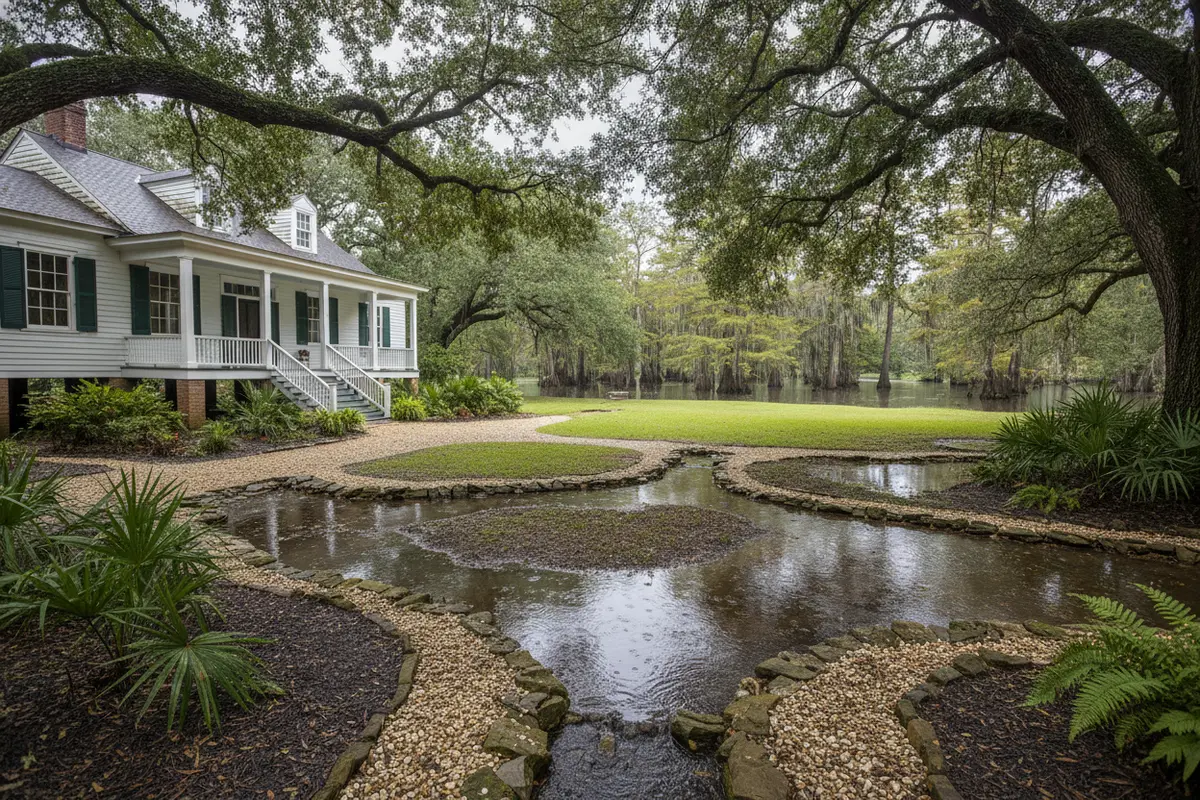
A flood policy is connected to a real building, not just a postcode. Construction details can affect how vulnerable the structure may be and the likely cost of repair. Information to gather includes the year built, foundation type, number of storeys, finished and unfinished areas. And the level of the lowest floor in relation to the ground or an established elevation reference. For a business, the building’s use and the way its space and equipment are arranged may also matter.
- Foundation and lowest floor: A slab, crawl space, pier, or other foundation can present different exposure. Be clear about the lowest floor and any enclosed areas below the main living space.
- Elevation and grading: Elevation information and the slope of the lot may help an insurer assess how water could reach the building. Provide documents only when they are accurate and applicable.
- Construction and age: Materials, building design, and the date of construction may be used in an insurer’s assessment. Do not guess if records can confirm the information.
- Building use: A primary residence, rental property, seasonal home, and commercial building may not fit the same policy form or eligibility rules.
- Prior flood damage or mitigation: Disclose relevant history and improvements accurately. Ask how the insurer treats repairs or mitigation rather than assuming a particular rating result.
Good records can make the quoting process more accurate. If you need to confirm details, check closing documents, a property survey, permit records, or information from your contractor. Any material changes, such as a renovation or change in building use, should be raised before the policy is issued or renewed.
How much is flood insurance after coverage limits and deductibles are selected?
Once the property details have been assessed, the requested protection also affects the policy cost. Building coverage and contents coverage are selected separately, so a homeowner should consider both the structure itself and the belongings kept inside it. The right balance depends on the property, how it is used, and the limits available under the policy form.
Replacement cost matters because it reflects the estimated cost to repair or rebuild the insured structure. FEMA identifies replacement cost value, the amount of coverage requested, and deductible choices as factors that influence the premium. Policies with higher coverage limits also carry higher potential loss costs. FEMA’s rating guide explains these relationships, but an actual policy review must follow the terms and conditions issued for the specific property.
Building and contents limits are different decisions
Building coverage generally addresses eligible parts of the structure, while contents coverage addresses eligible personal property. They are not interchangeable. Contents kept in a basement can also have restrictions under the Standard Flood Insurance Policy, including limits on certain finished surfaces and personal property. Review the definitions, exclusions, and settlement provisions rather than assuming that every item in the home is covered.
Deductibles change the out-of-pocket exposure
A higher deductible may reduce the overall premium, but it means paying more yourself after a covered flood loss. That choice should be realistic for your household or business, particularly if a flood could affect several parts of the property at once. Ask how the deductible applies, which coverage it affects, and whether separate terms apply to building and contents claims.
For anyone asking how much is flood insurance, the most useful comparison is not simply the lowest premium. Compare the selected limits, replacement cost basis, policy form, exclusions, deductible, and the amount you could afford to pay after a loss. Those details determine the protection the policy actually provides.
| Quote choice or detail | What to compare | Question to ask |
|---|---|---|
| Building limit | Covered building components, selected limit, and any applicable maximum | How was this limit selected, and what is not included? |
| Contents limit | Whether personal or business property is included, where it is covered, and sublimits | Are items in lower-level spaces treated differently? |
| Deductible | Amount applying to each relevant coverage and any separate deductible provisions | What would I pay before insurance responds to a covered loss? |
| Policy terms | Exclusions, waiting periods, claim conditions, and coverage definitions | When does coverage begin, and what conditions apply? |
The table is a starting point, not a substitute for the policy. Ask for the insurer’s written terms and check that the quote reflects the building and property you intend to insure. When assessing the home itself, our home insurance information can be a useful starting point for a broader property conversation. Flood insurance is a separate coverage consideration, so do not assume a homeowners policy includes it.
Does the type of flood policy matter?
Yes. Flood policies can follow different policy forms, and the differences may affect what is covered, how much protection is available, and how a claim is handled. The National Flood Insurance Program (NFIP) is a federal programme with its own rules and limits. Private flood policies are offered by insurers and may use different coverage structures, eligibility rules, exclusions, and claims provisions. Neither policy type is automatically right for every Louisiana property.
When comparing options, look beyond the headline premium. Read the policy form and check whether it covers the building, contents, or both. Confirm the coverage limits and ask how features such as detached structures, temporary accommodation, or improvements below the lowest elevated floor are treated. Terms can vary, particularly for basements, enclosed areas, personal property, and items stored at ground level.
Check exclusions and deductibles carefully
Exclusions are as important as covered causes of loss. A homeowners policy may exclude flood damage, so do not assume that existing home insurance provides the same protection as a dedicated flood policy. Review definitions, exclusions, conditions, and endorsements in the actual policy documents. A deductible is the amount you may pay before covered damage is considered. Check whether the deductible applies separately to the building and contents, whether it is fixed or percentage-based, and whether special deductibles apply to particular risks.
Timing also matters. Flood policies may have waiting periods, with exceptions that depend on the circumstances and policy rules. If a policy is being considered because of approaching severe weather, ask about the effective date and any waiting-period provisions before relying on it for protection.
For help understanding the questions to ask about flood insurance, contact GAMA Insurance Agencies. The team can discuss your general insurance questions and direct you to the appropriate information, without assuming that a particular flood policy or quote is available.
What should Louisiana homeowners compare before choosing?
Ask for more than a premium. Each quote should be tied to the same property and a clear set of coverage assumptions. A useful comparison includes the policy type, building and contents limits, deductibles, exclusions, waiting period or effective date, and any eligibility conditions. If a quote leaves a detail unclear, get clarification before relying on it.
- Confirm the property details. Verify the address, building use, age, foundation, floor levels, and any requested elevation information.
- Choose the protection to evaluate. Decide whether you need building coverage, contents coverage, or both, then identify the limits under consideration.
- Compare the deductibles. Note the amount and how it applies. A lower premium with a deductible you cannot comfortably fund may not fit your needs.
- Read the exclusions and conditions. Check how the policy defines flood, what property is excluded or limited, and what you must do to support a claim.
- Confirm timing. Ask when coverage can begin and whether a waiting period or other timing rule applies. Do not assume a new policy will cover an imminent storm or a loss that has already begun.
- Keep the documents. Save the quote, declarations, policy form, and supporting property records so you can check what was actually issued.
For a home purchase or a major renovation, include insurance in the planning process rather than leaving it until the last moment. Construction changes can alter the details used for a quote. For a rental home, explain that the property is tenant-occupied and ask how the policy treats the building and any owner-owned contents. A landlord policy and a tenant’s renters policy serve different purposes; neither should be assumed to cover every flood exposure.
What about flood insurance for a Louisiana business?
A business owner should think about more than the building shell. Equipment, inventory, furniture, records, and the cost of resuming operations may all affect the financial impact of a flood. Whether and how those exposures can be insured depends on the policy and the property. Ask the insurer to distinguish covered building property from business personal property, and confirm how items in lower areas or off-site locations are treated.
Business operations can also be interrupted while a damaged property is repaired. Do not assume a flood policy pays for lost income or extra expenses. Ask specifically whether business interruption or other time-element coverage is available for the flood exposure, what triggers it, and what waiting period, limit, or documentation applies. Those features may be addressed in a separate policy or endorsement, if offered.
GAMA offers business insurance and contractor insurance as part of its broader product portfolio. Those policies do not automatically include flood coverage, but our business insurance information and contractor insurance information can help begin a wider risk discussion. The right flood option depends on the property, business activity, insurer appetite, and policy wording.
How can you prepare for an accurate flood insurance quote?
Gather accurate information before you call. Having the relevant details in front of you can reduce follow-up and help make the comparison more meaningful. You may not have every item, and the insurer may not request all of them, but start with what is available.
- The complete property address and whether it is owner-occupied, rented, seasonal, or used for business.
- The building’s approximate year of construction, foundation type, number of storeys, and lowest-floor details.
- Any elevation certificate, survey, construction or renovation records, or other documents the insurer requests.
- The building limit and contents limit you would like to discuss, along with a deductible you could reasonably manage.
- Information about prior flood damage, repairs, or mitigation work, described accurately and supported by records when available.
- For a business, a basic inventory of equipment, stock, and other property that could be affected, plus questions about continuity and additional expenses.
Then ask the agent to explain the quote in plain terms. Which details drive the offered price? What assumptions are still unverified? Is the coverage building-only or does it include contents? What are the important exclusions? When would the policy take effect? An independent agency can seek options from multiple appointed carriers where available, but no agency can promise a specific premium, a particular insurer’s acceptance, or savings. Availability and terms can change.
For local support, learn more about a GAMA insurance specialist and see carrier information as part of your discussion. We have served Louisiana since 2004 and understand that insurance questions often come alongside practical storm preparations. We will help you identify the details to compare, while the insurer’s policy documents remain the source for coverage terms.
What should you clarify about flood coverage before you buy?
A quote is a snapshot of proposed terms, not the complete policy contract. Before accepting it, confirm that the named insured, property address, building description, and intended use are correct. Ask whether the quote is for a residence, rental property, or business use, and whether any detached structures are included or need separate consideration. A mismatch between the application and the actual property can lead to avoidable questions later.
Next, clarify what the policy calls a flood and how it treats the kinds of property you are concerned about. Water damage can have different causes, and insurance contracts may treat them differently. Ask for the relevant definitions and exclusions in writing. If you are worried about a particular feature, such as a finished lower level. A detached garage, a retaining wall, or equipment stored near the ground, name it directly. A general answer that the property is insured may not answer whether that specific item or circumstance is covered.
Check the scope and limits of any building and contents coverage. Ask whether the policy uses replacement cost, actual cash value, or another settlement method for the covered property, and confirm which method applies to each relevant category. The terms may not treat every type of property in the same way. If you own valuable equipment, specialised contents, or property used for work, do not assume the standard contents limit or definition fits your situation. Ask whether additional coverage is available and whether documentation or an endorsement is needed.
Timing deserves its own question. Find out the proposed effective date, whether a waiting period applies, and whether any exception is relevant to your circumstances. Do not wait until a storm is approaching to learn how long coverage takes to start. If you are buying a property, share the transaction timeline early and confirm the effective date with the insurer. A quote or application by itself is not proof that coverage is active; check for confirmation that the policy has been issued and is in force.
Finally, learn what you must do after a loss. Ask how to report a claim, what records to keep, and whether the carrier expects photographs, receipts, or other evidence. Keep a current inventory of important belongings and store copies of essential documents somewhere they can be reached if the home is inaccessible. These steps do not change the policy’s coverage or guarantee a claim outcome, but organised records can help you explain what was damaged and follow the insurer’s process.
These questions are especially useful when comparing multiple quotes. A clear comparison should show not only the premium but also the assumptions behind it, the deductible, the scope of covered property, and the important restrictions. If a term is unclear, request an explanation before deciding. Insurance is a contract, and the issued policy and endorsements control over a summary or verbal description.
Contact GAMA with your flood insurance questions
Call GAMA at (504) 305-4141 with general insurance questions
Frequently Asked Questions
Can I estimate my flood insurance cost from my neighbour’s policy?
A neighbour’s price is not a reliable estimate for your home. The properties may differ in elevation, construction, foundation, coverage limits, deductibles, policy form, and other rating details. Use another quote only as a prompt for questions, not as a substitute for a quote based on your address and building information.
Does being outside a high-risk flood zone mean I do not need coverage?
No map label can guarantee that a property will not flood. Flood exposure can occur in different locations and under different conditions. Review your property’s circumstances, mortgage or contract requirements if applicable, and potential financial exposure with a qualified insurance professional. The policy and insurer determine eligibility and coverage.
Will my homeowners policy pay for flood damage?
Do not assume it will. Homeowners policies commonly distinguish flood from other water damage, and exclusions and definitions vary by contract. Read your policy and ask the insurer what it covers. A separate flood policy may be needed for flood coverage, subject to eligibility and terms.
Can a higher deductible lower the flood insurance quote?
A deductible can affect a quote, but its effect depends on the insurer and policy. A higher deductible also increases the amount you would pay toward a covered loss. Compare the deductible alongside limits, exclusions, and the premium, and choose an amount you can manage.
When should I ask for a flood insurance quote?
Ask as soon as you are evaluating a property or reviewing your insurance, especially before a purchase or a planned change to the building. Coverage may not begin immediately, and waiting-period or effective-date rules can apply. Confirm timing with the insurer rather than expecting a policy to cover a loss that is imminent or already underway.