When you are asking what does homeowners insurance cover, the useful answer is that a policy may protect several different interests: the home itself, separate structures, belongings, personal liability and certain extra living costs after a covered loss. For background, read the home coverage overview.
Request a homeowners coverage review
In Louisiana, those protections matter in the context of severe storms, wind, heavy rain and other risks, but no single summary tells you exactly what your policy will pay. Coverage depends on the contract, endorsements, limits, exclusions, deductible and facts of the loss. We are an independent agency, so we can help you compare available carrier options and understand the questions to ask before choosing or changing a policy.
Contact GAMA to discuss your homeowners options
What does homeowners insurance cover in Louisiana?
Most homeowners policies are organised into coverage sections. Each section has its own purpose and limit. A loss may involve more than one section, and a claim decision depends on the wording of the policy and the circumstances. The Louisiana Department of Insurance describes homeowners insurance as covering the structure of a home and property, as well as personal legal responsibility for injuries to others. Review the Louisiana Department of Insurance homeowners insurance information alongside your policy documents.
The table below is a high-level guide, not a promise that a specific loss is covered. Actual terms vary by carrier and policy form.
| Coverage section | What it is generally for | Questions to check |
|---|---|---|
| Dwelling | The insured home and covered attached components | What structures and causes of loss are included? Is the limit adequate for rebuilding? |
| Other structures | Eligible structures separate from the home, such as a detached garage or fence | Which structures qualify, and what limit or exclusions apply? |
| Personal property | Covered belongings, subject to policy terms and special limits | Are items covered for replacement cost or actual cash value? Do valuables need separate coverage? |
| Personal liability | Certain covered claims alleging bodily injury or property damage for which an insured is legally responsible | Who is insured, what exclusions apply, and what limit is selected? |
| Additional living expense | Eligible extra costs when a covered loss makes the home unfit to live in | What triggers the benefit, how is it measured, and for how long can it apply? |
| Deductibles and exclusions | Rules affecting how a covered claim is adjusted or whether a loss is covered | Is there a separate deductible for a peril, and what losses are excluded? |
What does dwelling coverage protect?
Dwelling coverage is the part of a homeowners policy intended for the insured residence and certain components that form part of it. Depending on the policy wording, that can include the main structure, roof, walls, floors, built-in fixtures and attached features. Do not assume every item on the property is treated as part of the dwelling. Detached structures, land, outdoor property and improvements may be addressed elsewhere or may not be insured for every cause of loss.
A dwelling limit should be considered in terms of the cost to repair or rebuild the insured home after a covered event, not simply its sale price, tax assessment or mortgage balance. Rebuilding costs can be affected by the home’s size, construction, materials, age, design details and local labour and material availability. An insurance limit is not a guarantee that every rebuilding expense will be paid. Policy conditions, the selected limit and any applicable settlement provisions still matter.
When reviewing the dwelling portion, make sure the insurer has accurate information about the home. Note renovations, additions, roof updates, changes in occupancy and distinctive construction features. Ask what happens if repair costs exceed the dwelling limit and whether the policy offers any additional replacement-cost protection. These are contract-specific questions, so read the declarations and endorsements rather than relying on a general description.
Are detached structures covered?
Many homeowners policies include a separate coverage section for other structures. It may apply to eligible buildings or structures that are not attached to the main residence, such as a detached garage, shed, fence or gazebo. Whether a particular structure qualifies, and how much protection applies, depends on the policy language and limit.
Walk your property and make a list of detached structures and significant improvements. Mention a workshop, pool-related structure, large fence, guest house or other feature when requesting a quote or reviewing your policy. Do not assume a structure is covered simply because it sits on the insured property. Some uses, materials, construction conditions or specific causes of damage may be treated differently.
For a Louisiana home, also ask how the policy addresses wind-related damage and any separate deductible that may apply. The answer can vary by insurer and form. If a structure has a different use from the residence, explain that clearly so the coverage discussion is based on accurate information.
How does personal property coverage work?
Personal property coverage is generally intended for eligible belongings owned or used by an insured, such as furniture, clothing, electronics and household items, when damaged or lost because of a covered cause. The property section has a limit, and certain categories can have special limits. Cash, jewellery, collectibles, tools, business property, firearms and other specific items may be subject to restrictions that make a broad contents limit an incomplete guide.
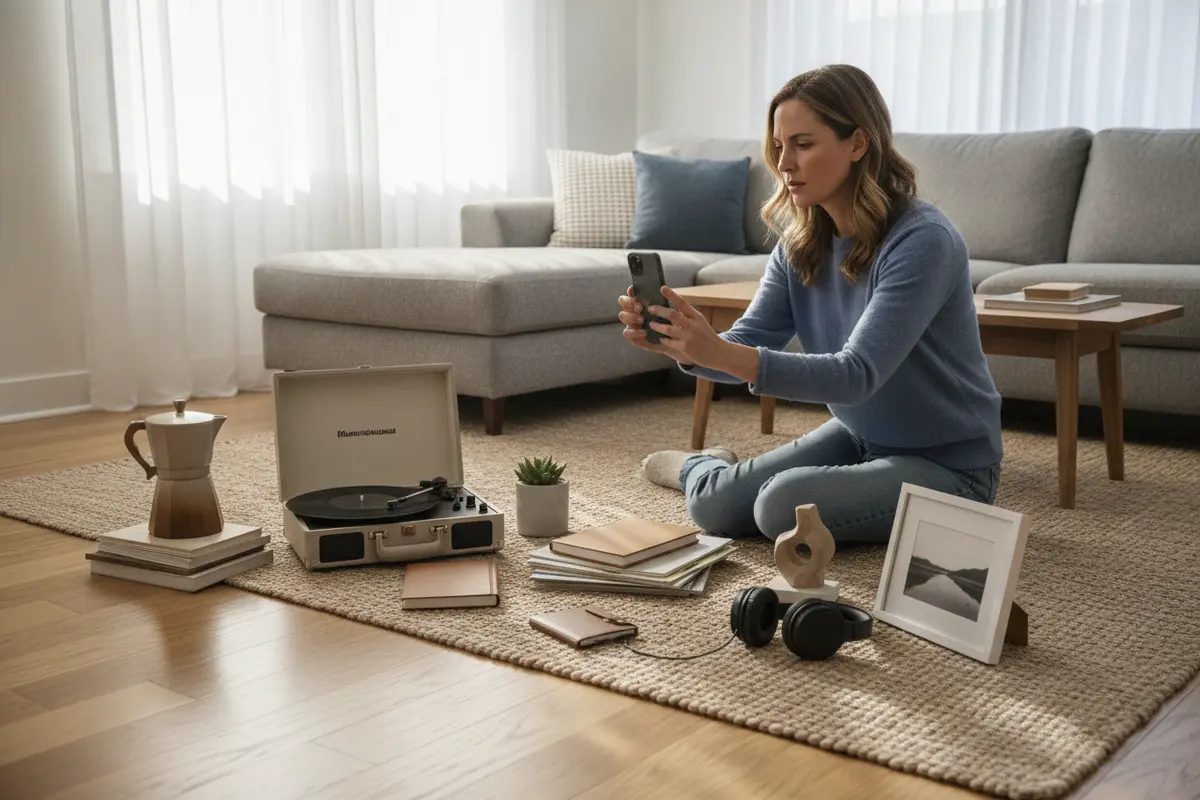
Take a practical inventory before a loss. Record major items, purchase details where available and photographs or video of rooms and storage areas. Keep the inventory somewhere you can access if the home is damaged. This does not change the policy terms, but it can help you describe what was in the home and organise information during a claim.
Ask whether personal property is settled on a replacement-cost basis or actual-cash-value basis for the applicable loss and item. Those terms can affect how depreciation is treated, and details vary by contract. Also ask whether belongings away from home are covered, which limits apply to high-value possessions, and whether scheduling an item or adding an endorsement is an option. Do not rely on a general description to confirm protection for a particular item.
For example, a policy might set a broad personal-property limit while applying a lower sublimit to a particular category. That is why it is worth listing valuable or unusual possessions and asking for the relevant terms in writing. If you are considering a home policy alongside another product, see our overview of home insurance options and ask how the specific carrier form treats your belongings.
What personal liability protection may cover
Personal liability coverage may help when an insured faces a covered claim alleging bodily injury or property damage for which that person is legally responsible. A policy may also provide some coverage for eligible legal defence costs, subject to its wording, conditions and limit. Liability coverage is different from coverage for damage to your own house or belongings.
Everyday examples can include an injury allegation following an accident on your property or accidental damage to someone else’s property. Whether the policy responds depends on the facts, who is insured, the nature of the claim and the exclusions. Intentional acts, business activities, certain vehicle-related incidents and other circumstances may not be covered under a homeowners liability section. The policy and its endorsements control.
Consider the limit in relation to your household circumstances and assets, but do not treat a general rule of thumb as personal advice. If you want to discuss broader liability planning, ask how a personal umbrella policy might coordinate with underlying policies and what minimum underlying limits apply. You can also review GAMA’s personal insurance lines and request a conversation about the options actually available to you.
When can additional living expense apply?
Additional living expense, sometimes described as loss-of-use coverage, may help with certain extra costs when a covered loss makes the insured home unfit to live in during repairs. Depending on the policy, eligible expenses might include a temporary place to stay and certain increased day-to-day costs above what the household would normally spend. It is not a general-purpose benefit for any inconvenience, evacuation or home repair.
Check what event must cause the home to be uninhabitable, how the covered period is determined, what expenses qualify and the applicable limit. Keep receipts and notes about expenses if you have a claim, and follow the carrier’s instructions. If the home remains usable, or the damage results from an excluded cause, the coverage may not apply. The insurer makes its determination under the policy terms and claim facts.
In Louisiana, a storm can disrupt normal arrangements even when the details of a loss are still being assessed. Keep policy information accessible, know how to contact your carrier and ask what documentation is useful. An insurance agency can help you understand the process and communicate with the carrier, but coverage decisions belong to the insurer and are governed by the contract.
How do deductibles affect a homeowners claim?
A deductible is the portion of an eligible covered loss that the policyholder is responsible for under the applicable terms. The amount and calculation depend on the policy. Some policies may use a flat deductible for certain claims and a separate percentage-based deductible for a specified peril. When a percentage deductible applies, ask which coverage limit is used as its basis and how the amount is calculated.
Do not assume that a deductible is the only out-of-pocket cost. A claim may involve excluded damage, limits, depreciation, uncovered upgrades or expenses that do not qualify. If the estimated damage is close to the deductible, consider discussing the process with your insurer or agent before deciding what to do. Report a loss as required by the policy and take reasonable steps to prevent additional damage, while keeping records of what you do.
- Find the deductible on the declarations page and check which peril it applies to.
- Look for separate wind, hail or named-storm language rather than assuming one deductible covers every loss.
- Ask how a percentage is calculated and whether the amount can change when the insured value changes.
- Review the deductible alongside your household’s ability to absorb an eligible loss.
- Confirm the carrier’s claim reporting instructions and deadlines in the policy documents.
What are common homeowners insurance exclusions?
A homeowners policy does not cover every kind of damage. Common limitations can include flood, gradual deterioration, maintenance problems, certain types of water damage, earth movement, intentional damage and losses connected with excluded activities. This is a general list, not a statement about any one carrier. Definitions, exceptions and available endorsements differ, and a claim may involve more than one cause.
Flood deserves particular attention in Louisiana. Standard homeowners coverage commonly excludes flood damage, but you must check your policy to confirm the actual terms and consider whether separate flood coverage is appropriate for your situation. Heavy rain, water entering a home and storm damage can raise difficult distinctions. The name used to describe an event does not determine coverage; the policy definition and the facts matter.
Other exclusions and limitations can apply even where the type of property is normally insured. For example, a loss may be limited by a special sublimit, a vacancy provision, a business-use exclusion or a requirement to maintain the property. An endorsement may broaden or change terms, but it does not remove every restriction. Read the exclusions and conditions, not just the coverage summary.
When comparing policies, ask the carrier or agent to explain any wording that is unclear. Request the applicable form or endorsement and ask for a plain-language explanation of the effect. Avoid relying on an informal assurance that a particular event is covered unless it is consistent with the written contract. A home-based business can raise questions about equipment, inventory, visitors and business liability, so disclose the activity and ask whether a homeowners policy is sufficient or whether separate business coverage should be considered. GAMA’s business insurance information can help you start that conversation, but the applicable policy terms determine coverage.
How can Louisiana homeowners review a policy before storm season?
A careful review is most useful before a claim, when there is time to correct information and ask questions. Start with the declarations page, then look at the policy form and endorsements. Make sure the named insureds, property address, occupancy, dwelling details, limits and deductibles are accurate. If you have made improvements or acquired valuable belongings, tell your agent or insurer and ask whether any policy changes are needed.
- Check the insured property. Confirm the address, construction details, roof information, occupancy and any detached structures.
- Review each limit. Consider dwelling, other structures, personal property, liability and additional living expense separately.
- Identify deductibles. Note any different deductible by peril and understand how a percentage-based amount is calculated.
- Read exclusions and endorsements. Pay attention to water, flood, wind, vacancy, maintenance and special limits relevant to your property.
- Document belongings and improvements. Keep an inventory, photographs and records of renovations in a secure place.
- Confirm how to report a claim. Keep carrier contact information available and understand the instructions in your policy.
Homeowners in Kenner, Metairie, New Orleans and Baton Rouge can face different property features and exposure conditions, so a neighbour’s policy is not a reliable substitute for reviewing your own. If you have a second residence, rental exposure, a home-based business or a major renovation, mention it. Accurate details help an agent look for options that match the risk presented to the insurer. If household decisions include vehicle protection, you can also review GAMA’s auto insurance information and ask whether comparing home and auto options makes sense for your circumstances. For details about combining those lines, see the home and auto insurance page. Different policies remain subject to each carrier’s underwriting, terms and eligibility rules.
We have served Louisiana households as an independent agency since 2004. An independent agency can compare options from multiple carriers, subject to its appointments and underwriting availability. That does not mean every carrier will offer every coverage or that one policy is best for everyone. We can help you compare limits, deductibles and policy differences and explain what to verify in the final contract. Learn more about our home insurance information or contact us to start a review.
How do you compare homeowners policies?
Price is one part of a comparison, but it cannot show whether two policies offer equivalent protection. Compare the contract terms, not just the headline limit. The following questions can help you organise a review:
- Are the dwelling limits and settlement provisions comparable?
- Are roof and other building losses settled under the same terms?
- Are personal belongings covered at replacement cost or actual cash value, and what special limits apply?
- Are wind, hail or named-storm deductibles different?
- How does each policy define water damage, flood and other relevant causes of loss?
- What are the liability and additional living expense limits?
- Which endorsements are included, optional or unavailable?
- What information or maintenance conditions could affect a claim?
Use the same property details and coverage preferences when seeking more than one quote. Otherwise, differences in the information supplied can make the comparison misleading. Ask for clarification in writing when a coverage distinction matters to you, and keep the final policy documents with your household records.
What should you do after damage to your home?
If your home is damaged, protect people first and follow instructions from emergency officials. When it is safe to do so, take reasonable steps to prevent further damage, such as arranging temporary protection for an opening, but do not put yourself at risk or begin permanent repairs before you understand the carrier’s process. Keep notes about what happened and when, and take photographs or video of visible damage before moving or discarding affected items where it is safe and practical.
Contact the insurer promptly using the claim reporting instructions in your policy. Be prepared to provide the policy number, property address, a description of the event and a way to reach you. Ask what documentation the adjuster needs, whether temporary repairs should be documented, and what records to keep for eligible additional living expenses. Save receipts and copies of messages, estimates and reports. Follow the insurer’s directions about inspection and repair decisions, and keep a copy of all claim communications.
A claim outcome is based on the contract, the evidence and the circumstances, not merely on the name assigned to a storm or type of water. If you disagree with an explanation, ask the insurer to identify the relevant policy language and describe how it applies. An agent can help you understand the process and relay questions, but cannot promise a claim result or replace the insurer’s coverage determination.
Discuss your coverage before storm season
Call us before renewal to discuss your policy questions and keep your declarations page nearby so we can focus on the limits, deductibles and terms you want to understand.
Frequently asked questions
Does homeowners insurance cover hurricane damage in Louisiana?
A policy may cover certain hurricane-related damage, but coverage depends on the cause of damage, policy wording, exclusions, limits and deductible. Wind damage and flood damage are not automatically treated the same way. Review the specific wind or named-storm deductible and ask the carrier how the policy addresses the type of damage you are concerned about.
Does homeowners insurance cover a roof leak?
It depends on what caused the leak and the policy terms. Sudden damage from a covered event may be treated differently from gradual wear, poor maintenance or deterioration. A claim is assessed using the facts and applicable exclusions, so document the damage and contact the insurer for claim instructions rather than assuming every leak is covered.
Are belongings covered outside the home?
Some policies extend personal property coverage away from the residence, but limits, exclusions and conditions may apply. High-value property or property used for business can have different treatment. Check the policy or ask about the specific item and location before relying on that protection.
Does homeowners insurance include flood insurance?
Do not assume it does. Flood damage is commonly excluded from standard homeowners policies, and separate flood coverage may be needed. Read the policy definition and exclusions, and ask about appropriate options for your property and circumstances.
Can I change limits or deductibles after buying a policy?
You can ask your agent or insurer about a change, but the available options, effective date and underwriting requirements depend on the carrier. Request updated documents and check that any change is in force before relying on it.
Contact us for homeowners coverage information
Call GAMA to discuss your policy questions and keep your declarations page nearby so we can focus on the limits, deductibles and terms you want to understand.
Homeowners insurance can help protect several parts of your financial picture, but the written policy determines what applies to a particular loss. Review the contract before you need it, ask specific questions and revisit coverage when your home or household changes.